
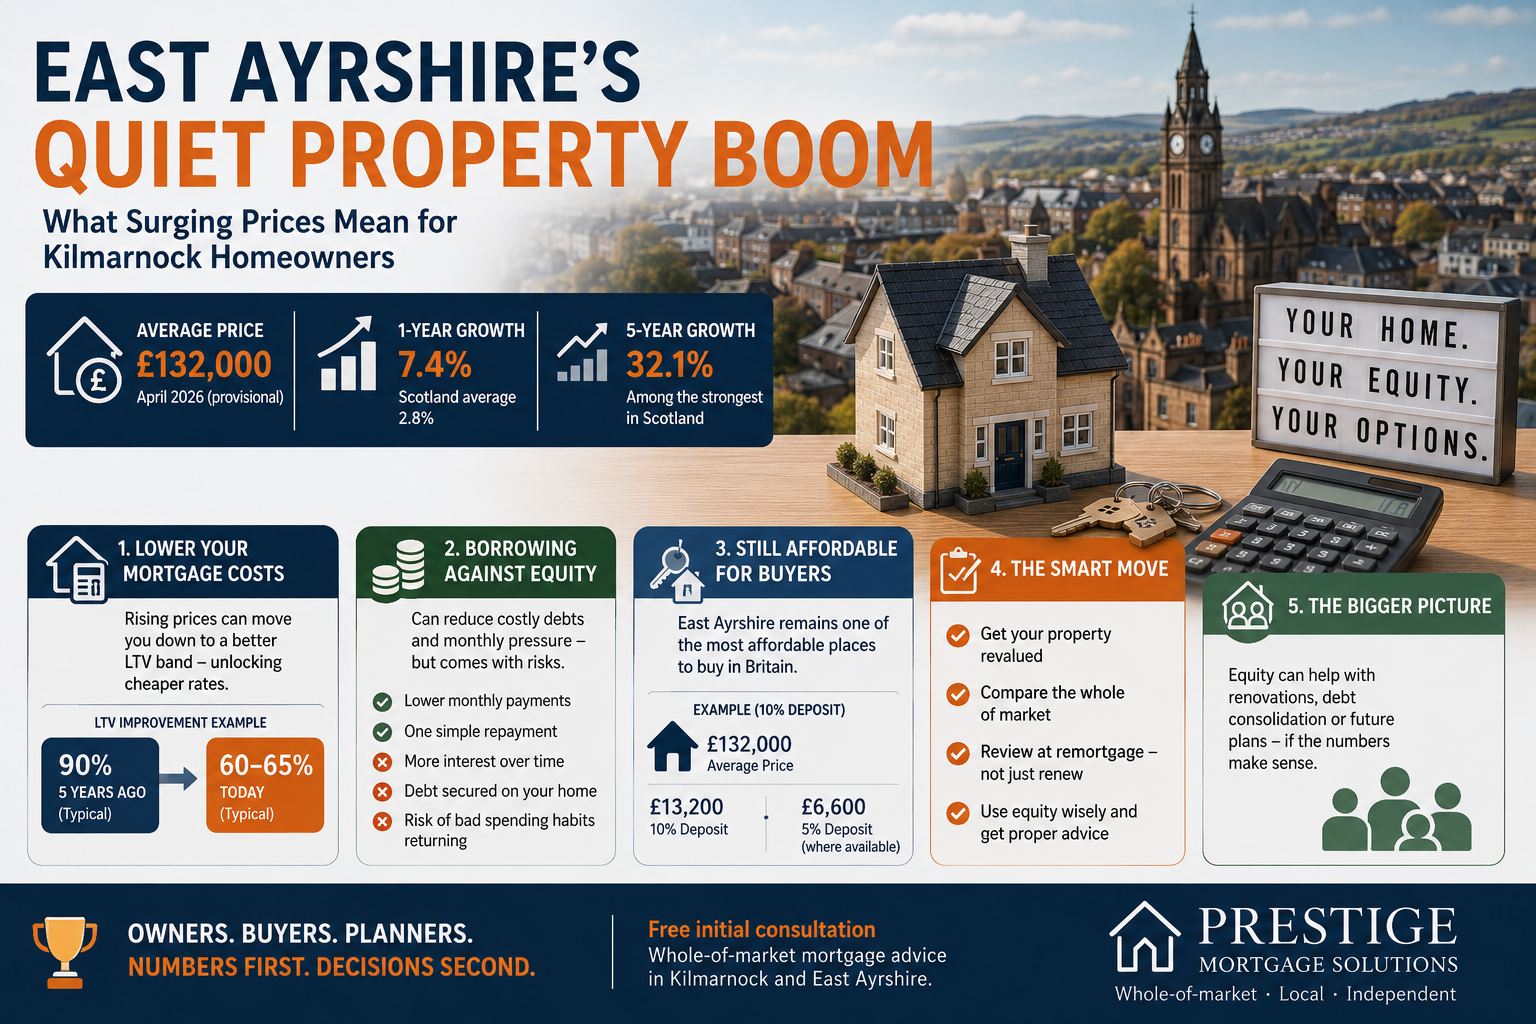
While the property headlines have spent years fixated on Edinburgh’s prices and Aberdeen’s slide, one of Scotland’s strongest housing markets has been hiding in plain sight in the west. According to the UK House Price Index for Scotland (Registers of Scotland, April 2026, provisional), the average house price across East Ayrshire reached £132,000 — up 7.4% in a single year, nearly three times Scotland’s 2.8% average rise, with five-year growth of 32.1%, among the strongest in the country.
For buyers, that’s a market getting away from them. But for the tens of thousands of existing homeowners in Kilmarnock and its surrounding towns, it means something else entirely: a substantial, largely unexamined improvement in their household balance sheet. The question is what — if anything — to do with it.
The Mechanics: Why Rising Prices Cut Your Mortgage Costs
Mortgage pricing runs on loan-to-value (LTV) bands. Borrow 90% of your home’s value and you pay one rate; get that loan below 75% of the value and you unlock materially cheaper products. Most homeowners understand that overpaying the mortgage moves them down the bands. Fewer register that the house doing the work moves them down too.
Consider a Kilmarnock homeowner who bought five years ago with a 10% deposit. With 32% local price growth since, plus five years of capital repayments, their original 90% LTV loan may now sit at 60–65% LTV — the territory where lenders offer their most competitive rates. If they fixed their mortgage back then and simply renewed with the same lender without a revaluation, there’s a fair chance they’re being priced off an equity position that no longer exists.
The fix costs nothing: when your current deal approaches its end, get the property revalued as part of a whole-of-market remortgage review, rather than accepting the renewal quote that assumes yesterday’s value. A broker such as Prestige Mortgage Solutions, which advises homeowners across Kilmarnock and East Ayrshire, can run exactly this check — current value, current LTV band, best available product across dozens of lenders — typically starting with a free initial consultation.
The Temptation: Borrowing Against the Boom
Rising equity brings offers. Homeowners with growing equity are prime targets for “consolidate your debts into your mortgage” marketing, and it’s worth being clear-eyed about what that transaction really is.
The appeal is genuine: mortgage rates sit far below credit-card and personal-loan rates, so rolling £15,000 of expensive debt into the mortgage can slash the monthly outgoings — sometimes by hundreds of pounds. For a household under real monthly pressure, that relief can be the difference between coping and not.
But three things change when unsecured debt becomes secured. First, the term: £15,000 repaid over three years at a high rate can cost less in total interest than the same £15,000 stretched over the 20 remaining years of a low-rate mortgage. Second, the security: debt that was previously just a credit-file problem if things went wrong is now attached to your home. Third, the habit: consolidation clears the cards but not the behaviour that filled them — and refilled cards on top of an enlarged mortgage is the worst of both worlds.
None of this makes consolidation wrong. It makes it a decision that deserves honest, both-sides-of-the-ledger advice — total cost over the full term, not just the monthly saving — from an adviser obligated to show you the risks, not just the relief. Book a FREE Appointment now.
For Buyers: The Window Is Narrowing, Not Shut
It’s worth saying plainly: even after a 7.4% surge, East Ayrshire remains one of the most affordable places in Britain to buy a home. A £132,000 average means a 10% deposit of £13,200 and a 5% deposit — where lenders offer it — of £6,600. Kilmarnock’s rail links to Glasgow keep it firmly in commuter range, which is precisely what’s driving the growth. For first-time buyers weighing up whether to wait, five years of 30%-plus growth suggests the market is unlikely to get cheaper by waiting; on these entry prices, buying sooner and building equity in a rising market has a strong recent track record locally.
The Bottom Line
Booms this quiet rarely stay quiet. East Ayrshire’s growth has already repriced Kilmarnock’s housing stock; the only question is whether individual homeowners collect their share of the benefit. For owners, that means a proper revaluation and whole-of-market review at the next remortgage — not a rubber-stamped renewal. For those eyeing their equity for renovations or consolidating debts, it means advice that prices the full term, not the first month. And for buyers, it means a still-affordable market with visible momentum. In all three cases, the winners will be the ones who run the numbers before the market runs further — and with free initial consultations from Prestige Mortgage Solutions Ltd widely available from whole-of-market advisers, there’s little excuse for guessing at figures a professional can confirm in an hour.
